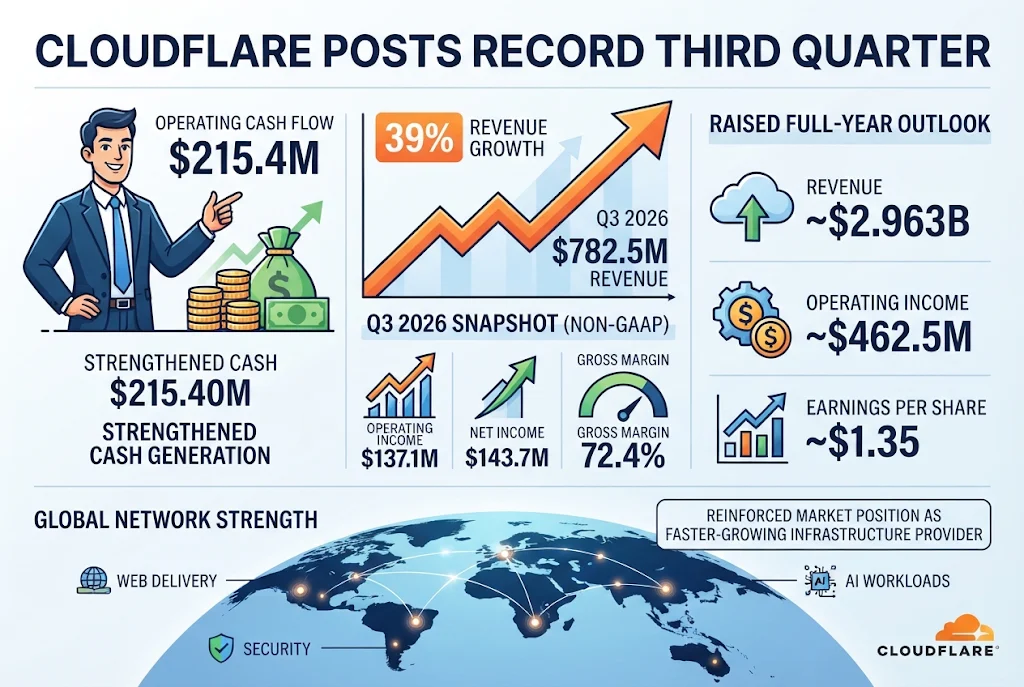
Cloudflare reported third-quarter 2026 revenue of $782.5 million on November 5, up 39% from a year earlier, in what co-founder and CEO Matthew Prince called “Cloudflare’s best quarter ever.” Prince said the company accelerated growth, delivering its fastest revenue growth in nearly four years while expanding profitability. The quarter also pushed Cloudflare past $3 billion in annualized revenue.
Profitability reached a new high. Non-GAAP operating income was $137.1 million, up 60% from $85.9 million a year earlier, and the 17.5% non-GAAP operating margin is the highest in the company’s history, up 370 basis points from the prior quarter and 220 basis points from a year ago. Non-GAAP net income was $143.7 million, or $0.38 per diluted share. On a GAAP basis, the company reported an operating loss of $67.9 million and a net loss of $34.1 million, or $0.10 per share, and it expects GAAP profitability in the fourth quarter.
Customer growth was a standout. Cloudflare added more than 158,000 paying customers in the quarter, up 110% year over year, and now has about 5,000 customers paying more than $100,000 a year, up 25% from a year ago. It added 308 of those large customers in the quarter, and large customers contributed 75% of revenue, up from 73%. Dollar-based net retention rose to 122%, up from 120% in the prior quarter and 119% a year ago, according to GuruFocus’s summary of the earnings call. Sales productivity set a record for the 11th consecutive quarter of year-over-year growth.
Growth was broad across regions. The United States made up 52% of revenue and grew 44%, EMEA made up 26% and grew 32%, and APAC made up 14% and grew 32%. Remaining performance obligations, a measure of contracted future revenue, reached $2,877 million, up 34% from a year earlier, and current remaining performance obligations rose 37%.
Cash generation strengthened. Operating cash flow was $215.4 million, up from $167.1 million a year earlier, and free cash flow was $82.1 million, or 10% of revenue, compared with $75.0 million in the third quarter of 2025. Cloudflare ended the quarter with $5.13 billion in cash and available-for-sale securities, after issuing $2.5 billion and repaying $1.3 billion of convertible senior notes during the period. GAAP gross margin was 71.2%, and non-GAAP gross margin was 72.4%, within the company’s long-term target range of 70% to 77%.
Cloudflare is investing in its network as demand grows. Network capital expenditures were 15% of revenue in the quarter, and the company expects them to be 14% to 15% of revenue for the full year. Operating expenses fell to 55% of revenue, down 510 basis points from a year earlier, with sales and marketing at 35% of revenue, research and development at 13% and general and administrative at 7%. Headcount was about 4,700 at the end of the quarter.
The outlook points to continued momentum. For the fourth quarter, Cloudflare expects revenue of $845.0 million to $846.0 million, up 38% from a year earlier, non-GAAP operating income of $156.0 million to $157.0 million, and non-GAAP earnings of $0.43 per share on about 379 million weighted average shares.
For the full year, the company now expects revenue of $2.963 billion to $2.964 billion, up 37% from 2025, non-GAAP operating income of $462.0 million to $463.0 million, and non-GAAP earnings of $1.35 per share on about 376 million weighted average shares.
The results reinforce Cloudflare’s position as one of the faster-growing infrastructure providers in the cloud and security market, as its global network serves customers’ web delivery, security and AI workloads. With accelerating growth, record operating margin, a rising count of large customers and a multibillion-dollar cash position, Cloudflare enters the final quarter of the year with room to keep investing in its network and product portfolio.
Leave a Reply